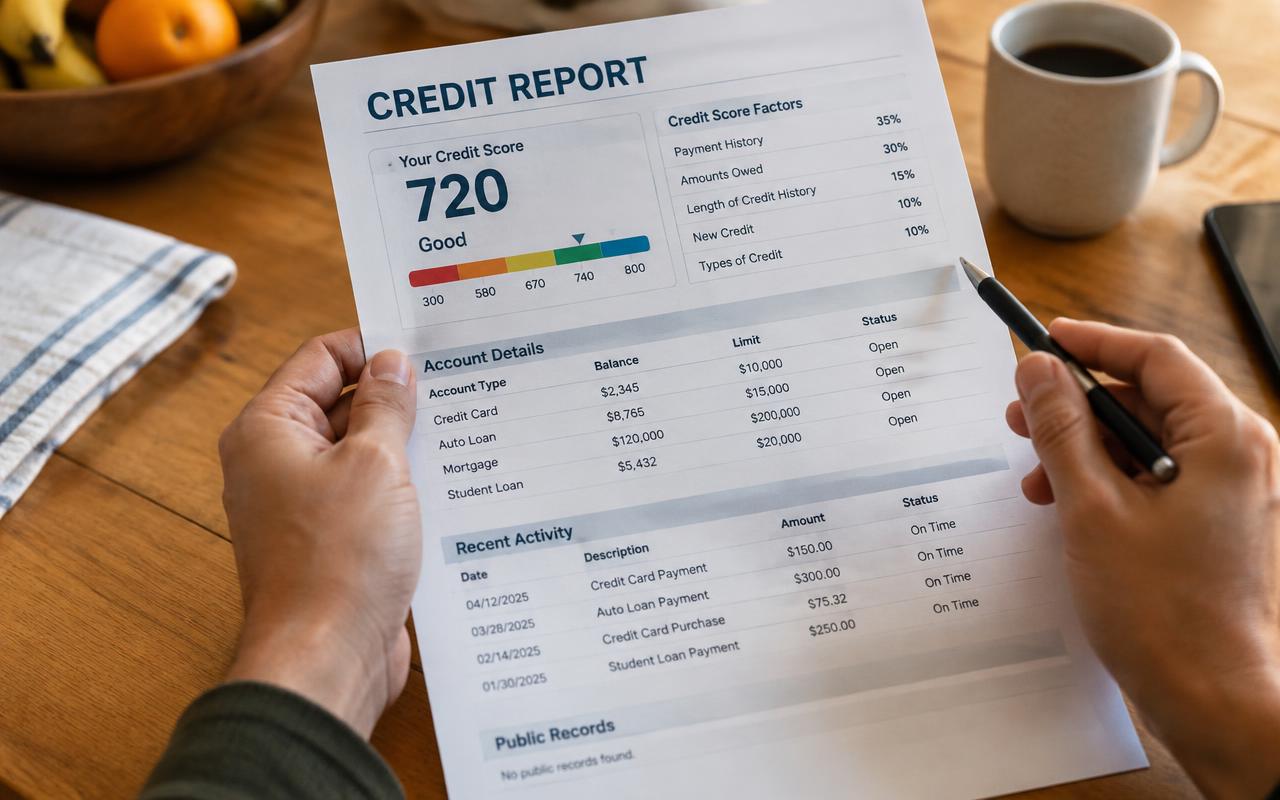
Most people skim their credit report and miss the errors that matter. Use this 10-point audit checklist to find every inaccuracy across all three bureaus.
Here's the mindset shift that separates people who fix their credit from people who don't: you are not "fixing credit." You are auditing data.
A credit report is a database entry built by dozens of companies typing information into automated systems. Errors are common. Your job is to check every line the way an accountant checks a ledger, then challenge only what is wrong.
Set up your audit sheet
Open a spreadsheet with one row per account and these columns:
- Creditor: Name as shown on the report
- Account # (last 4): To match the same account across bureaus
- Equifax / Experian / TransUnion: Balance, status and late dates as each bureau shows them
- Date of first delinquency: When the account first went late and never recovered
- Problem found: The specific inaccuracy, in one line
- Evidence: Statements, letters, bank records that prove it
Putting the three bureaus side by side is the whole trick. When one bureau says $1,240 and another says $2,105 for the same account, at least one of them is wrong.
The 10-point audit checklist
1. Accounts that aren't yours. Could be identity theft or a "mixed file" where someone with a similar name or SSN got merged into your report.
2. Wrong balances or credit limits. A missing credit limit can make a card look maxed out and inflate your utilization.
3. Duplicate accounts. The same debt listed twice, often once by the original creditor and once by a collector, both showing a balance.
4. Wrong late-payment dates or counts. Compare against your own bank records. A payment you made on time but that posted late is still worth a dispute if you can prove it.
5. Old addresses or name variations tied to negative accounts. These often point to a mixed file.
6. Charge-offs with a balance that keeps changing. A charged-off account that was sold should usually show a $0 balance with the original creditor.
7. Collections with the wrong original creditor or amount.
8. Items past the reporting window. Most negative items must come off 7 years after the delinquency began, plus 180 days (15 U.S.C. 1681c). Chapter 7 bankruptcy can stay 10 years.
9. Hard inquiries you don't recognize.
10. Bankruptcy records with wrong details, such as the wrong chapter, filing date or discharge status.
Pay special attention to the date of first delinquency
This one date controls how long a negative item can legally report. If a collector reports a later date than the real one, the item stays on your report longer than the law allows. This is called "re-aging," and it's worth checking on every collection and charge-off.
Separate errors from accurate negatives
At the end of your audit, sort every negative item into one of three buckets:
- Inaccurate: wrong data you can point to. These go into your dispute letters.
- Accurate but paid or old: candidates for a goodwill request (Article 6) or simply waiting out the clock.
- Accurate and unpaid: these need a plan, not a dispute.
This matters. The FTC says no one can legally remove accurate, timely negative information, and lists "telling you to dispute accurate information" as a credit repair scam red flag (FTC). Bureaus can also stop investigating disputes they find frivolous. Honest, specific disputes win more often than blanket ones.
Your next step
Your "Inaccurate" bucket is your Round 1 dispute list. Article 3 shows you how to send it.
Found something that doesn’t add up? Start here
Download the free starter guide for a clearer starting point on what to challenge, what to pay, and what to tackle first.
This article shares general tips. It is not legal or money advice for your own situation. Results are different for each person.