Start repairing your credit yourself
Download our free DIY starter guide for practical steps on disputes, utilization, and deciding what to challenge or pay.
3 pages. No payment required. Download it instantly.
Three steps from denied to approved
Fixing credit is not complicated when someone shows you the order. Here's how every CreditAhead client moves through the program.
Review your reports
Week 1We pull all three bureau reports, flag every inaccurate, outdated, or unverifiable negative item, and build a dispute strategy around your specific goal — home, car, cards, or funding.
Dispute and rebuild
Weeks 2–12Custom dispute letters go to the bureaus and creditors. At the same time we coach you on utilization, payment timing, and adding positive accounts so the score climbs from both directions.
Protect and monitor
OngoingMonthly report re-imports, progress updates when items come off, and a call every time your score moves up. You'll know exactly where you stand before you apply for anything.
Credit services built to get you approved
Whether you need full dispute work or just a straight answer on what to do next, there's a fit.
We challenge inaccurate, outdated, or unverifiable collections, charge-offs, late payments, and inquiries with the bureaus and creditors — and keep going round after round until the report is clean.
See what can be removed →One-on-one guidance to understand your report, manage balances, and build a long-term plan. For people who don't need heavy dispute work but want a clear roadmap and someone to call before they apply.
Get your roadmap →Three-bureau monitoring so every change shows up fast. When something comes off, you'll hear from us. When something new appears, we handle it before it costs you an approval.
Start with a free assessment →See the changes for yourself
Score updates, dispute responses, and removals — captured from real client reports.
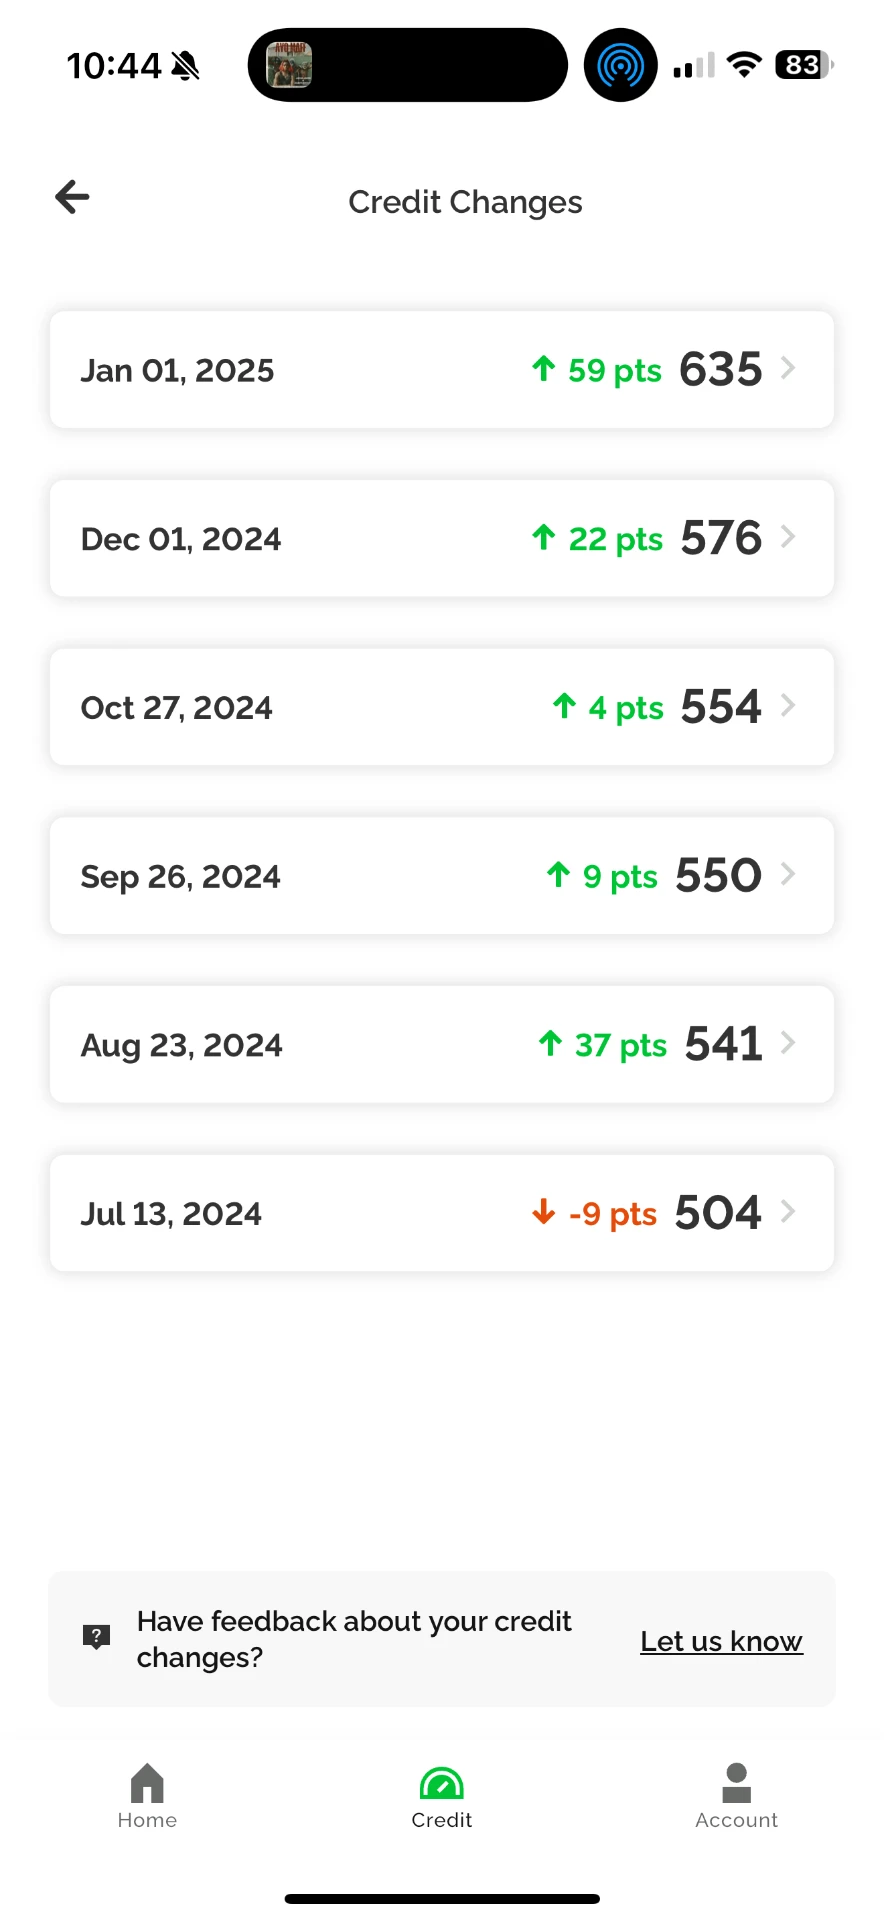
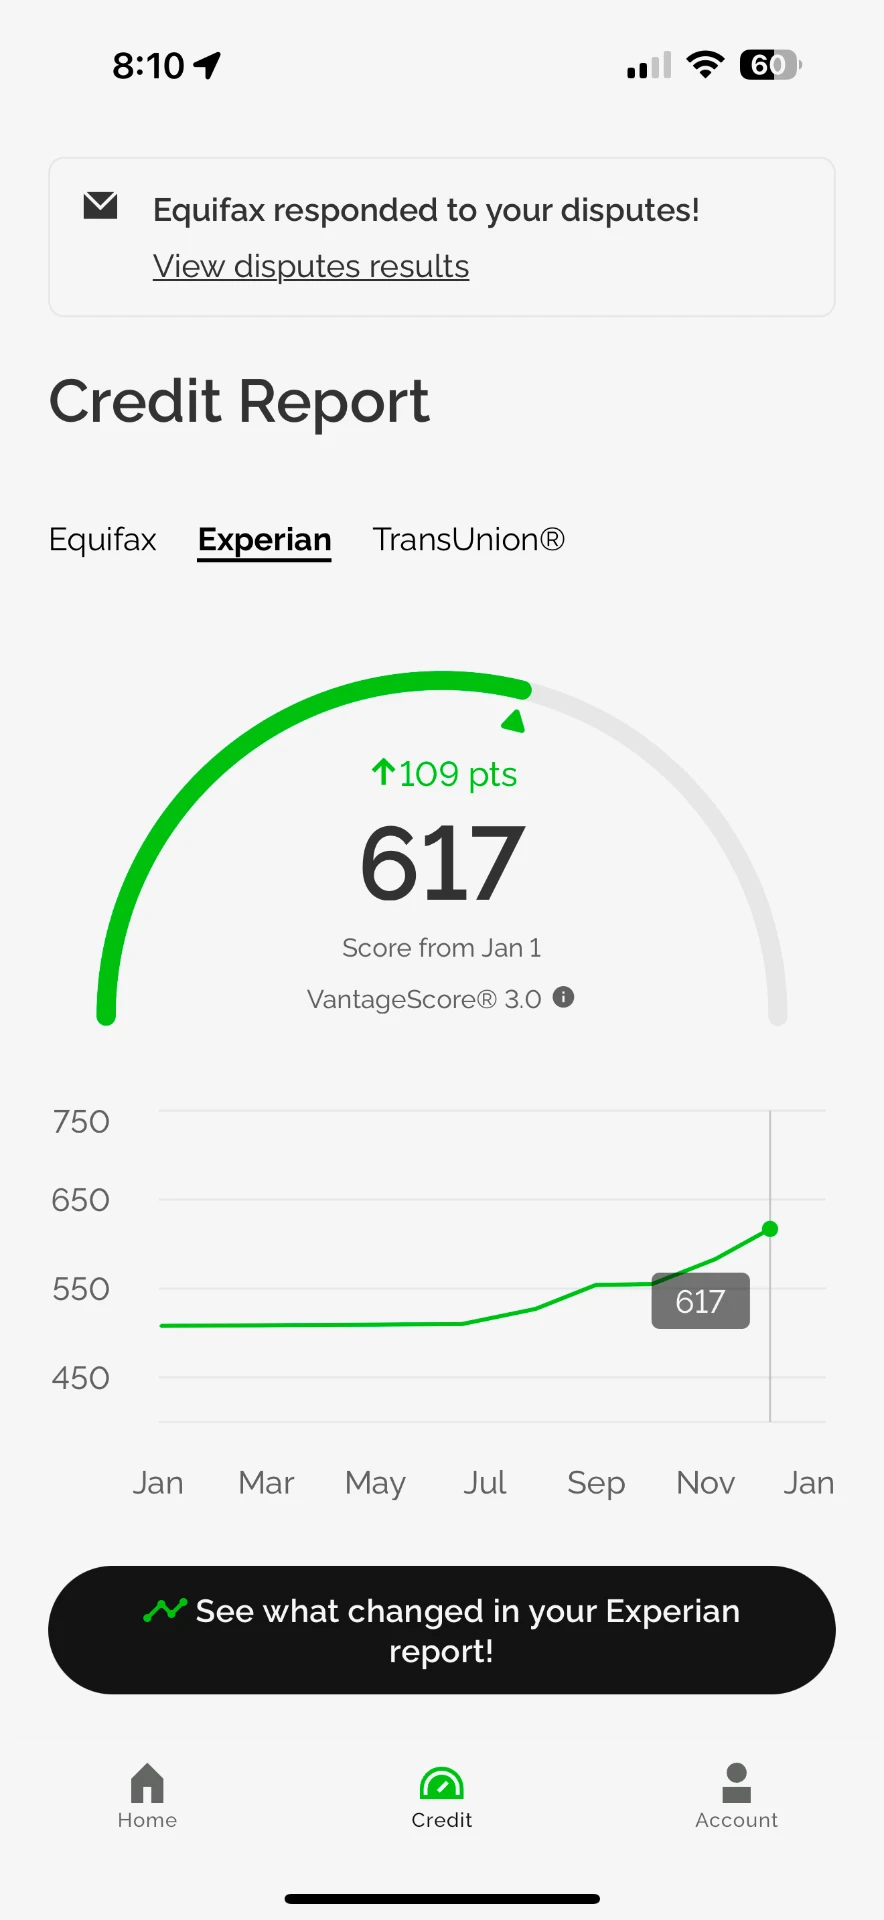
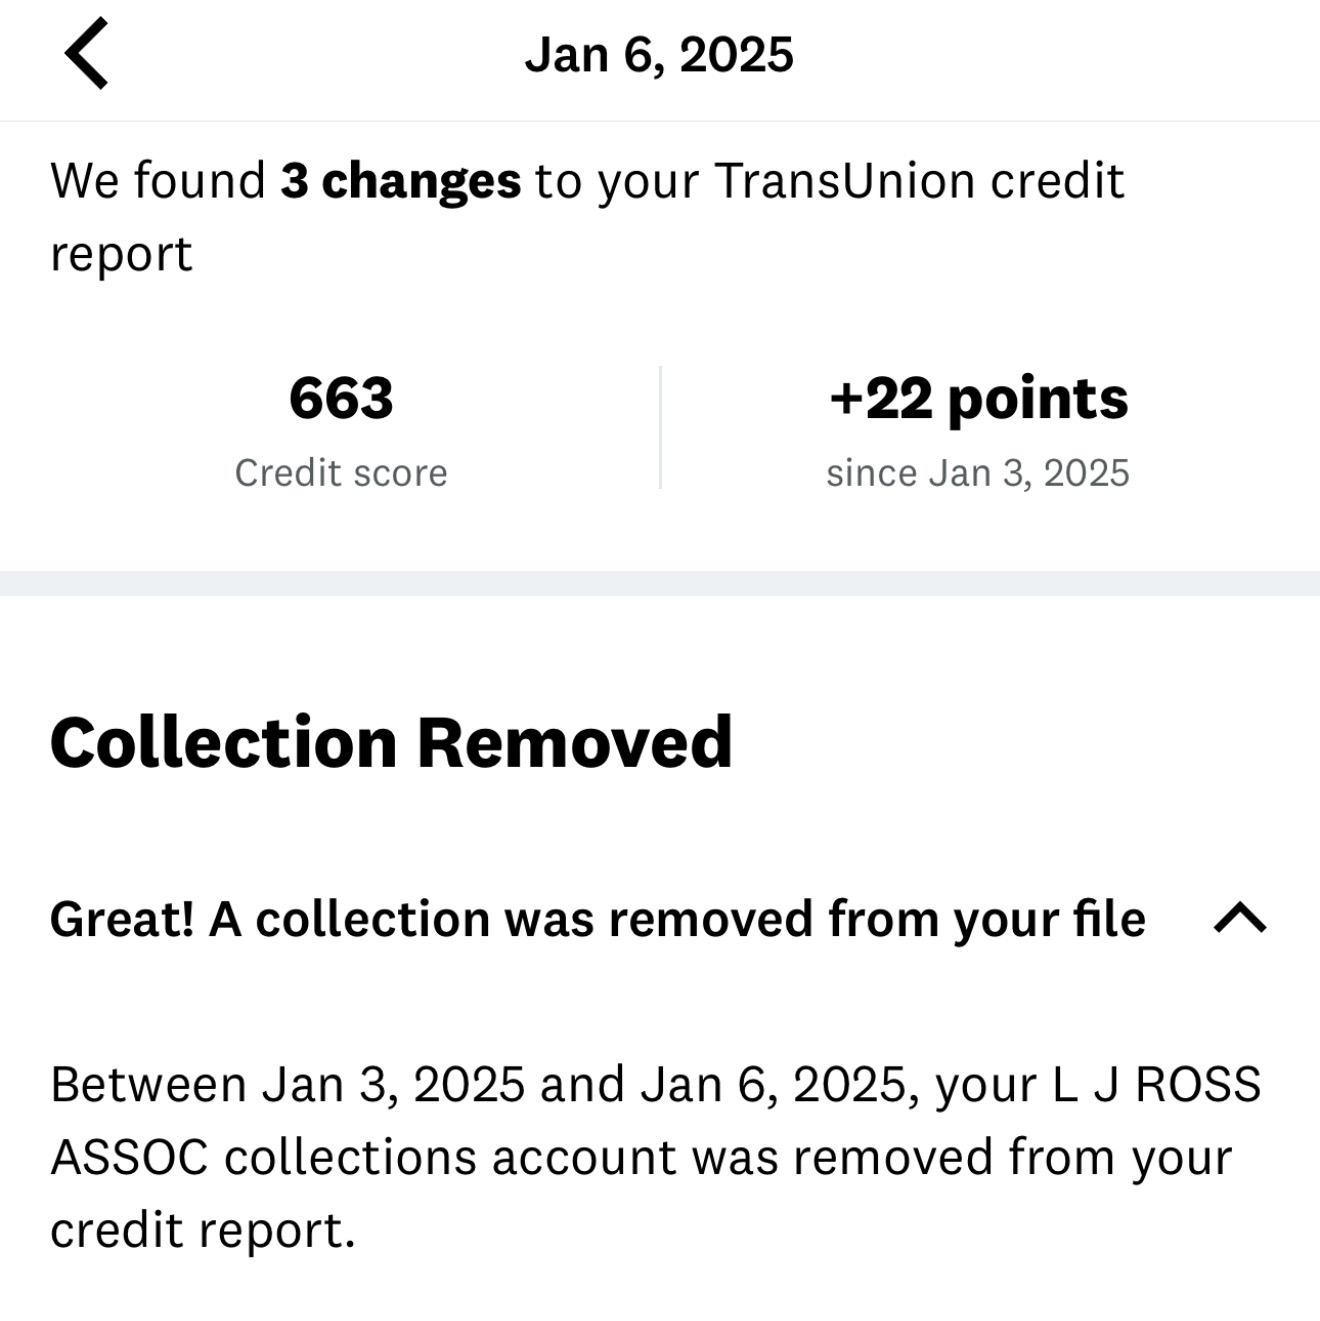
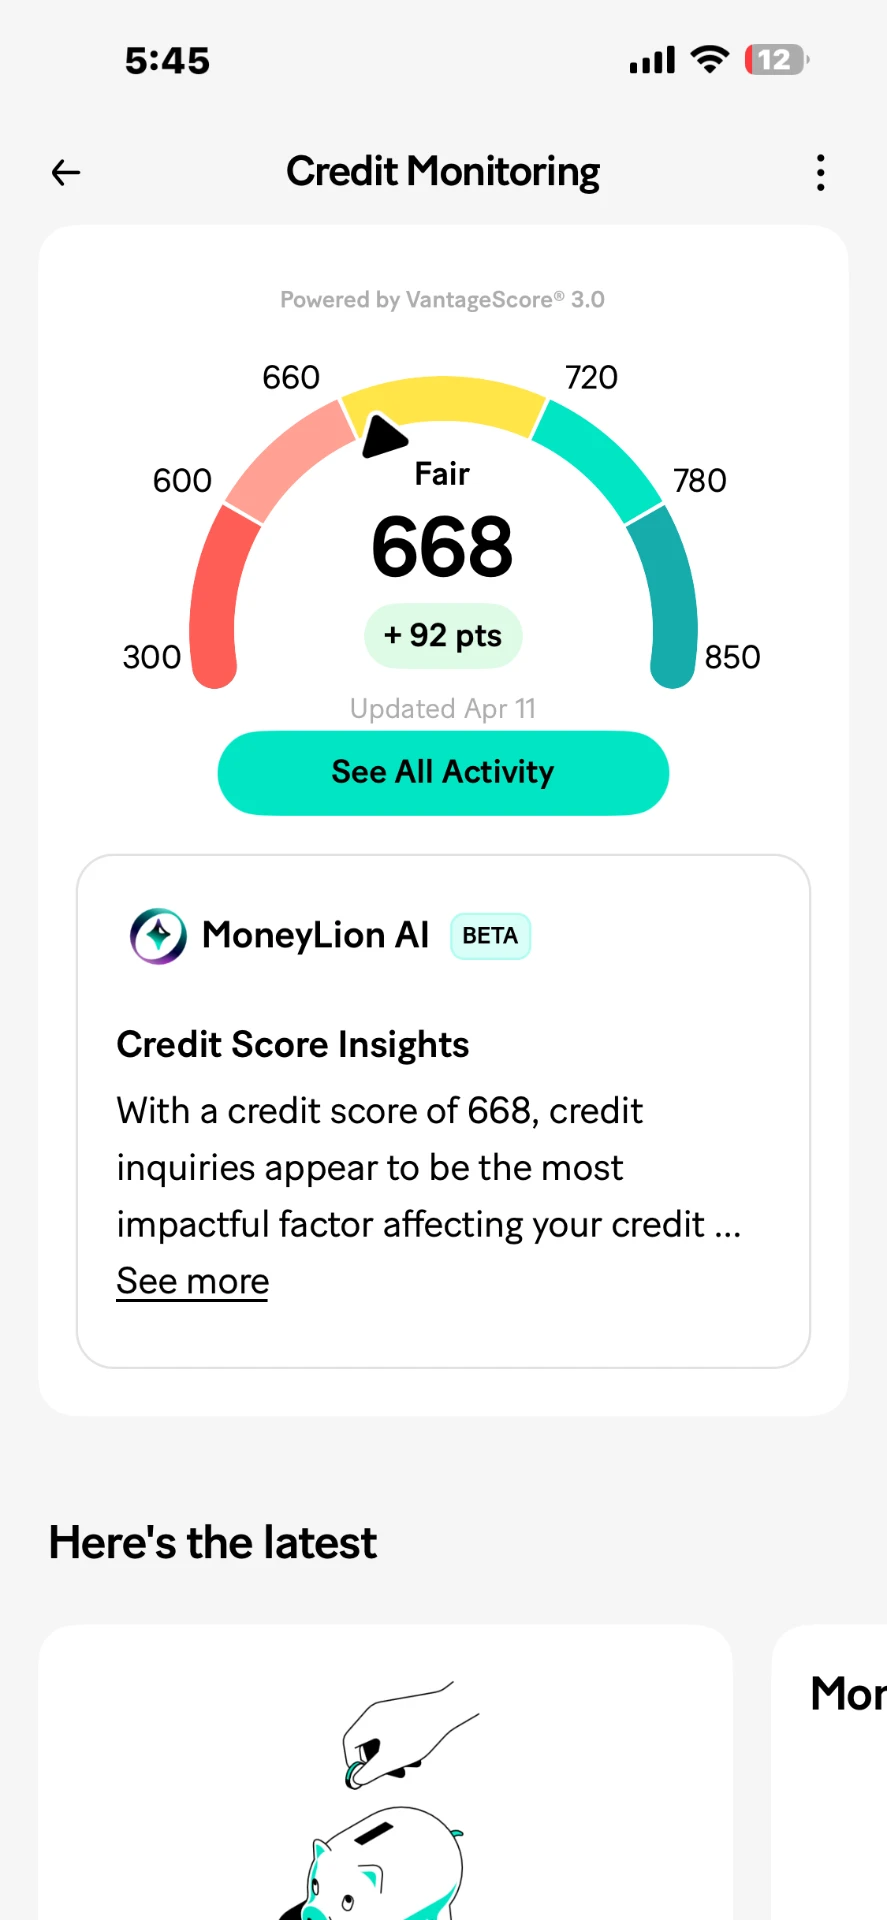
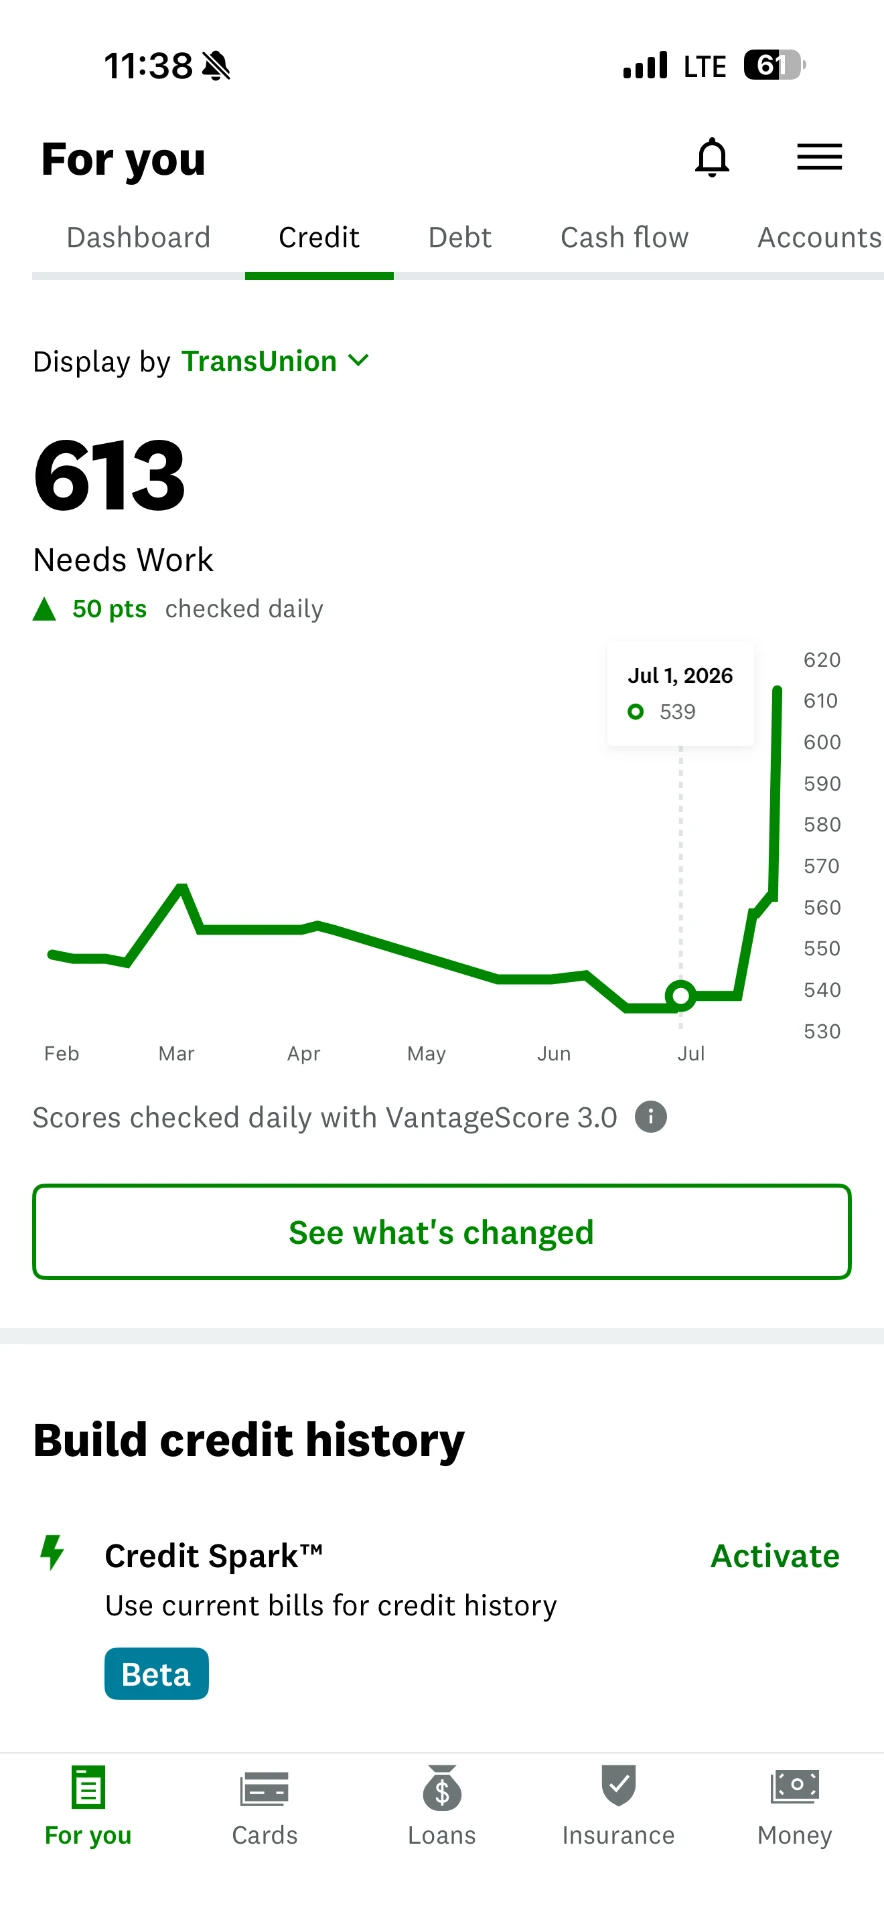
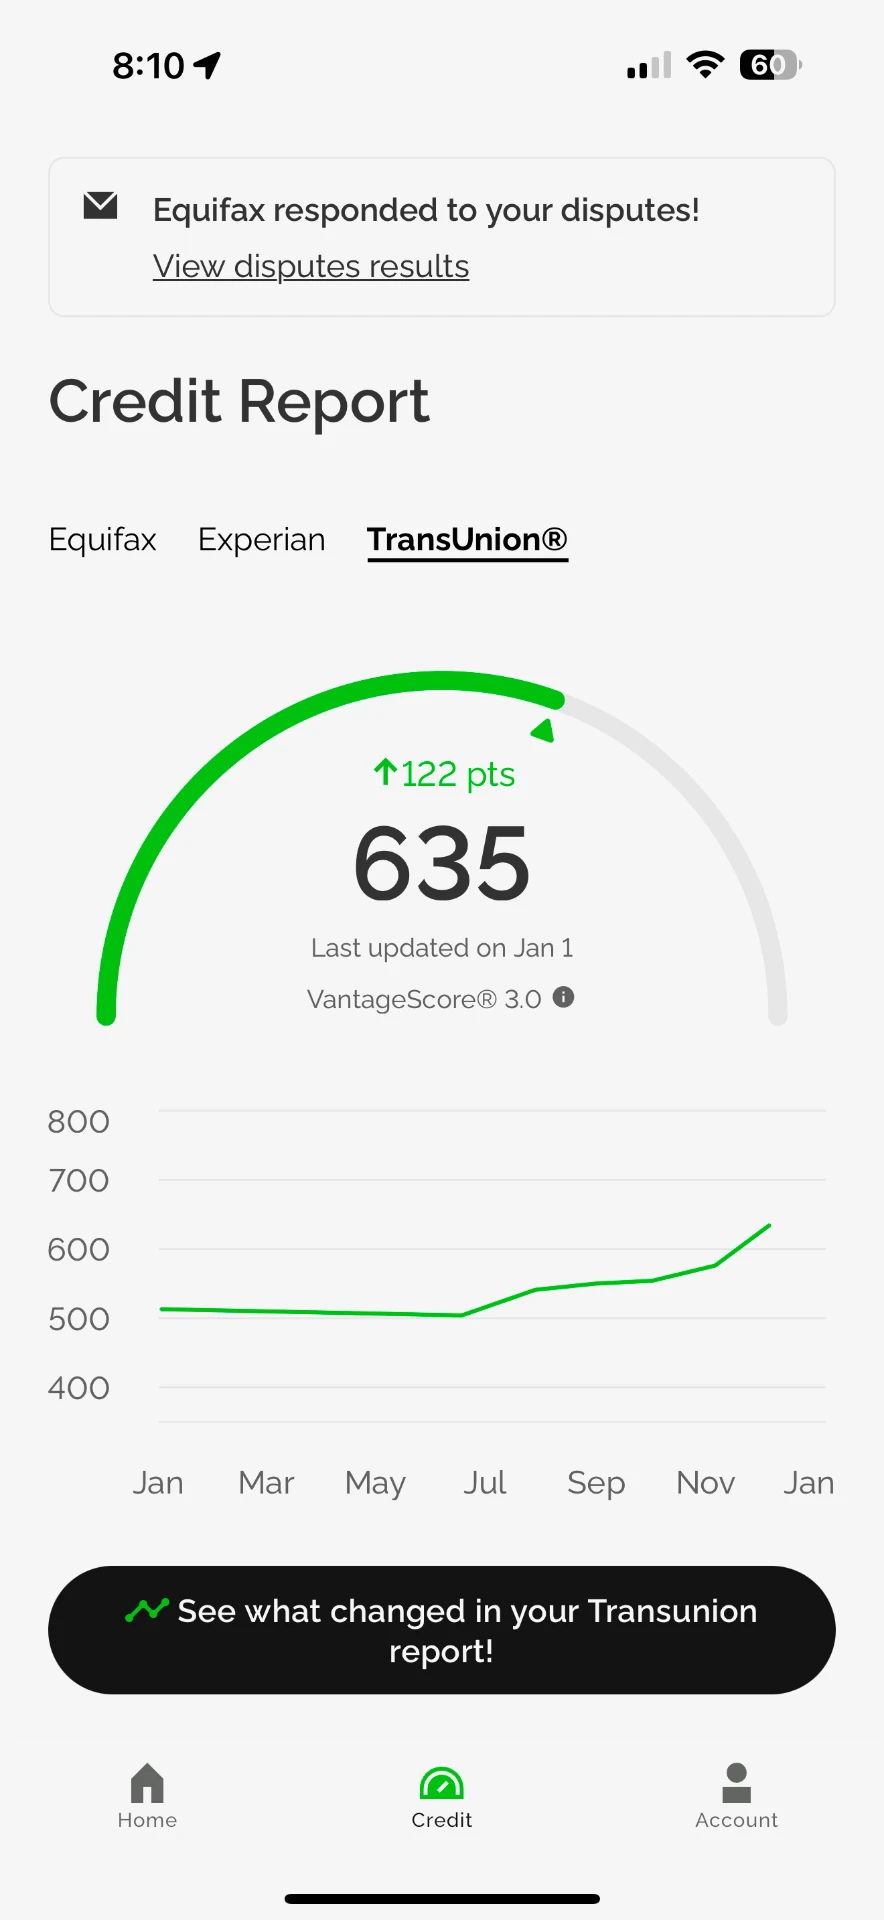
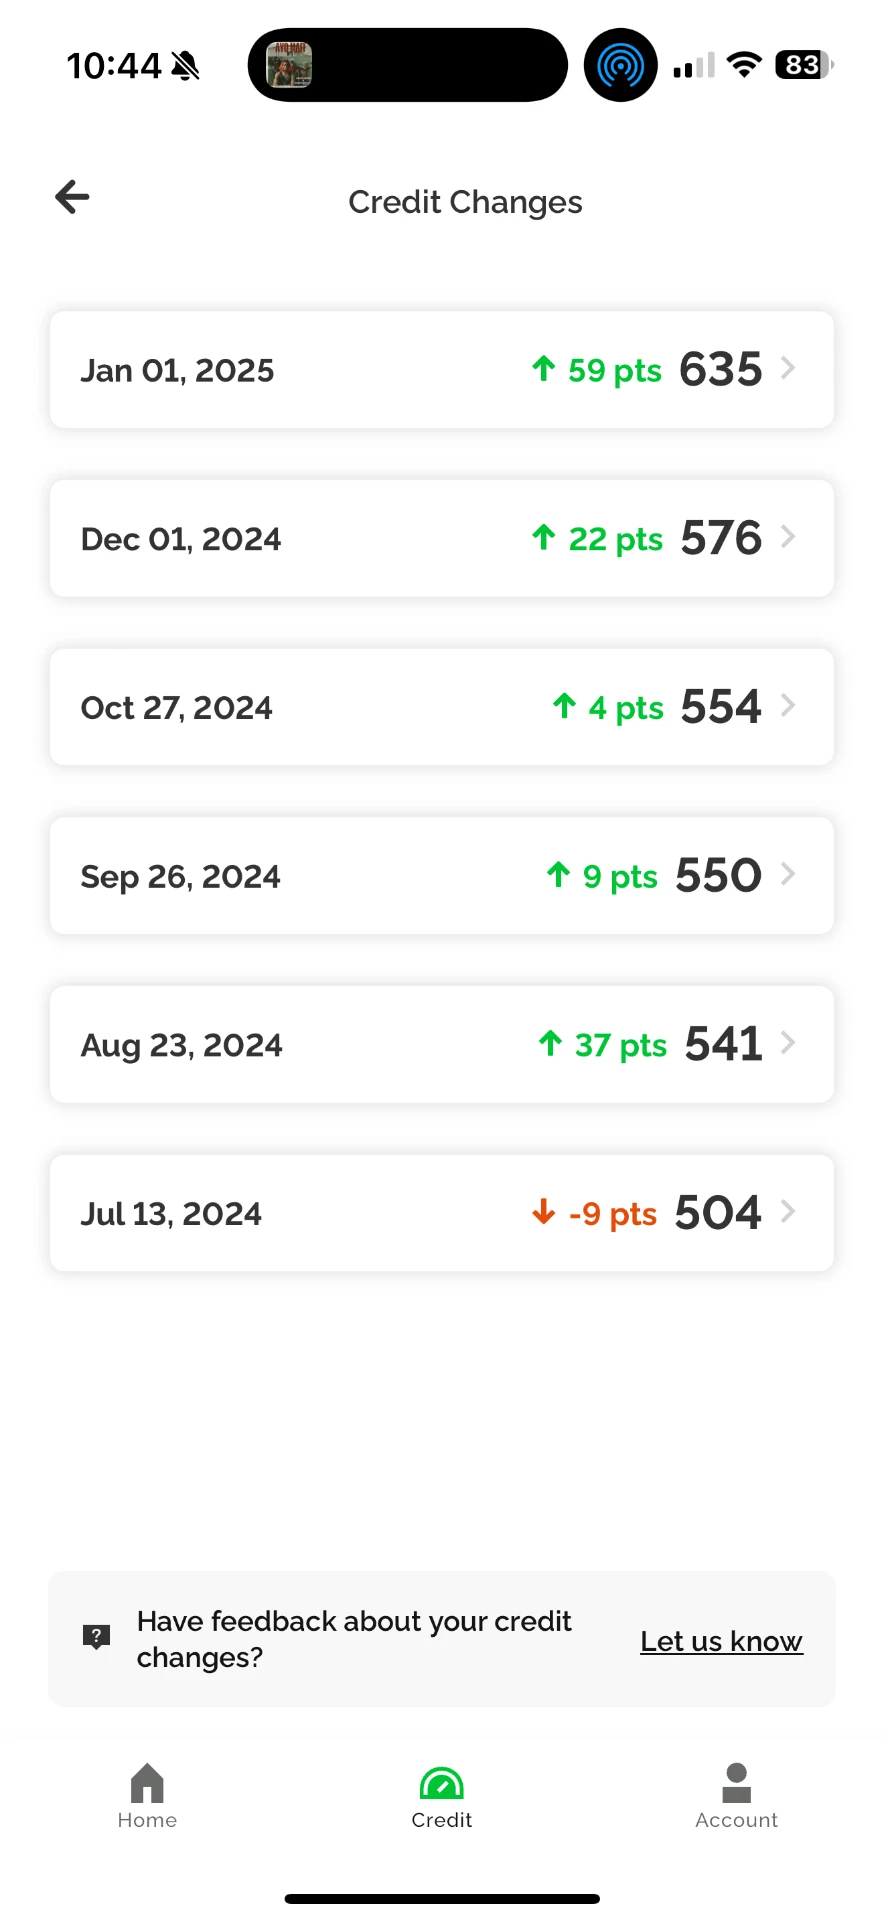
Real client results shared with permission. Every credit profile is different — results vary and are not guaranteed.
CreditAhead was built because bad credit costs more than a number
CreditAhead (formerly Safesky Consulting) is a service of Safesky Digital LLC, working with clients nationwide. We started this because we have lived both sides of credit — and we know exactly how much the bad side costs, even when the bill never shows up in the mail.
Damaged credit is quiet. It is the higher interest rate on the car you needed yesterday. It is the security deposit on an apartment, the card carrying 24% APR because it is the only one that approved you, and the pre-approval that comes back $80,000 lower than the home you pictured. It is years of overpaying while you tell yourself you will deal with it next month.
We also know what the other side feels like. Walking into a dealership and choosing the car instead of settling for whatever financing approves you. Getting the credit card with the limit you actually want. Booking a trip on points, refinancing into a rate that makes you smile, and watching a lender compete for your business instead of the other way around.
That is not a fantasy — it is what happens when your report is clean and your score works for you. Our job is to get you there.
- Written agreement firstFull description of services and your right to cancel before you pay anything.
- Compliant by designWe follow the Credit Repair Organizations Act and never dispute accurate information.
- Three-bureau approachEquifax, Experian, and TransUnion — because they rarely match.
- Real people, real hoursMon–Fri 9am–8pm ET. Call (239) 645-1620 and a coach picks up.
Credit, explained plainly
Charge-Offs Explained: How to Audit and Dispute Them the Right Way
A charge-off doesn't mean the debt is gone, and it doesn't always mean it's reported correctly. Here's how charge-offs work, where errors hide, and how to dispute them.
Read the guide →Collections on Your Report? Validate Before You Pay a Dime
Before you pay a collection account, make the collector validate it. Here's how the FDCPA's 30-day window works, what paying actually does to your credit, and how to handle medical debt.
Read the guide →
Bankruptcy on Your Credit Report: What You Can Actually Dispute
You can't erase a bankruptcy you filed, but you can make sure it, and every account it touched, is reported correctly. Here's what to check and how to dispute it.
Read the guide →How to fix bad credit
Bad credit is rarely one problem. It's usually a mix of items that shouldn't be on your report, balances reporting too high, and a thin file with nothing positive to offset the rest. Fixing it in the wrong order wastes months.
Get the free repair guide- 01
Get all three reports
Equifax, Experian, and TransUnion rarely match. The bureau with the error is often the one setting your rate, so you can't work from one report.
- 02
Dispute what shouldn't be there
Inaccurate, outdated, duplicate, or unverifiable items — collections, charge-offs, late payments, and inquiries. Bureaus get 30 days to respond, so this runs in rounds.
- 03
Drop your utilization
Get every card under 30% of its limit, ideally under 10%. This is the fastest lever on the list and can move a score in one statement cycle.
- 04
Never miss a due date again
Payment history is the heaviest factor. Autopay the minimum on everything, then pay the rest manually.
- 05
Add positive history
A secured card or a reported installment account gives the score something to grow on while the disputes work.
- 06
Re-check before you apply
Pull updated reports before any mortgage, auto, or card application. Applying into a stale file is how good plans get wasted.
Local to Southwest Florida, working nationwide
Pick your area to see how we work with clients there.
What people ask before they start
Straight answers, no sales script. Anything else, call (239) 645-1620 or email us — a coach replies the same business day.
01Does the assessment affect my credit?
No. The assessment is based on your answers. Nothing is pulled until you enroll, and enrollment uses a soft pull through credit monitoring, which does not affect your score.
02How fast will I see results?
Bureaus have 30 days to respond to a dispute, so the first changes usually show in the 30–45 day window. Utilization changes can move a score within one statement cycle. Timelines depend on what's on your report.
03Can you remove accurate negative items?
We dispute items that are inaccurate, outdated, unverifiable, or reported incorrectly — which describes a surprising share of what's on most reports. Anything accurate and verifiable stays, and we'll tell you that up front rather than sell you a promise.
04What do I need to get started?
A phone call and about 15 minutes. We'll set up your monitoring, pull the reports, and walk you through what we found before any dispute goes out.
05Is there a contract?
You'll receive a written agreement and a full description of services before you pay anything.
06How long does it take to fix bad credit?
Each dispute round takes about 30 days because that's the window bureaus have to respond, so most reports need several rounds. Utilization and payment-timing changes can move a score in a single statement cycle. Our program runs six months, which is enough time for multiple dispute rounds plus a rebuild plan that holds.
07How do I fix bad credit on my own?
Pull all three reports, list every negative item, and dispute anything inaccurate, outdated, or unverifiable directly with the bureaus — you can do this yourself for free. Then get every balance under 30% of its limit, never miss a due date, and add one positive account. Most people come to us because the disputes stall or the reports don't match, not because it's impossible.
Start with the free DIY guide
Get practical credit repair steps now, then explore the complete playbook when you're ready.
Instant download · No payment required · Prefer to talk? (239) 645-1620